Costs
Why do Mastiffs cost more to insure?
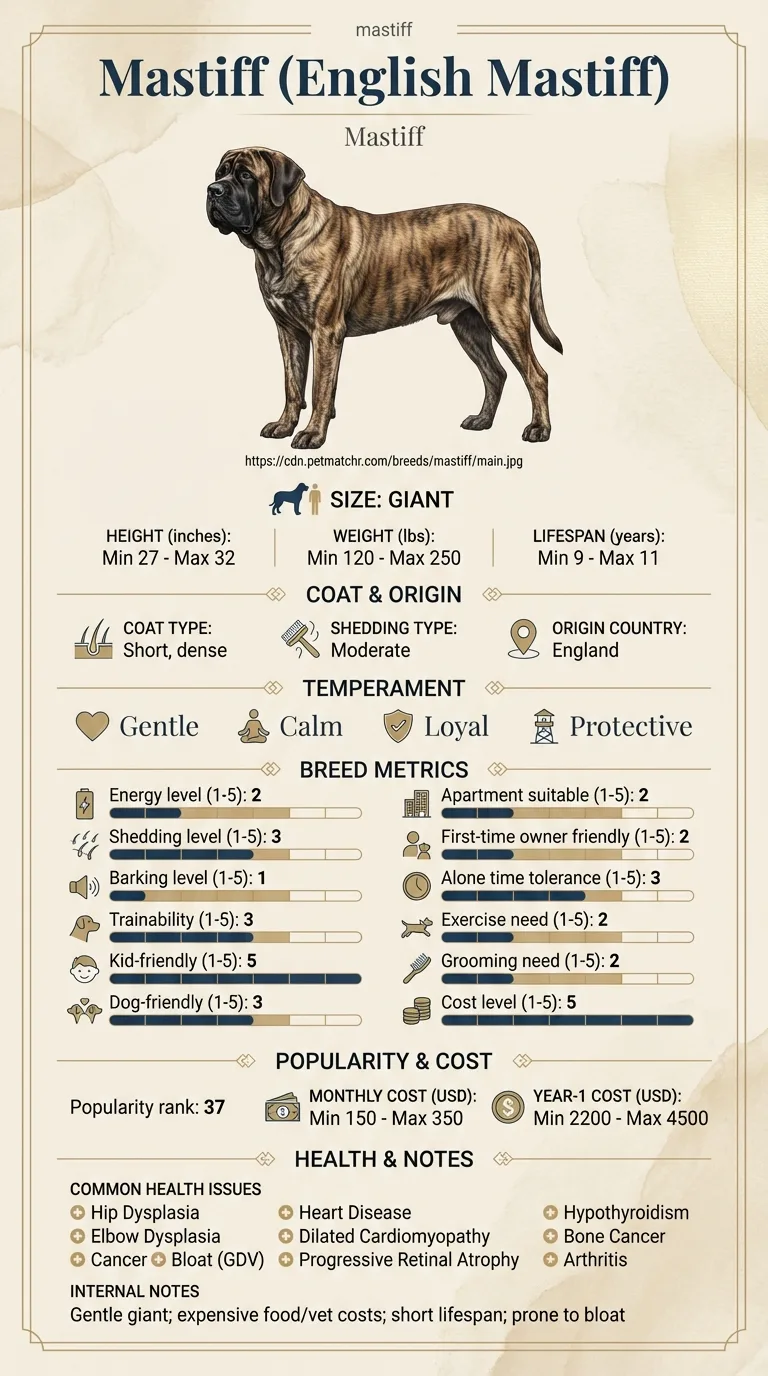
Their documented risks skew toward expensive categories such as bloat surgery, joint disease, cardiac care and cancer, and body weight inflates the price of every drug and procedure.
Quick answer
Why do Mastiffs cost more to insure?
Their documented risks skew toward expensive categories such as bloat surgery, joint disease, cardiac care and cancer, and body weight inflates the price of every drug and procedure.
Giant breeds do not claim more often. They claim bigger, and the policy decisions that matter are the ones you make before anything happens.
Owners choosing a policy for a Mastiff puppy, and existing owners who have discovered mid-claim that their annual limit or their exclusions were not what they assumed.
This guide is not medical advice. If your dog shows pain, sudden behavior change, or worsening symptoms, consult a licensed veterinarian.
Some links may be affiliate links. We may earn a commission at no extra cost to you. We only suggest products we believe are helpful for dog owners.
We research and check what we publish, but we do not warrant that any figure, date, price, or statement is accurate, complete, or current, and we accept no liability for any loss, cost, injury, or other harm arising from the use of this site. Use it as one reference among several. You remain responsible for your own decisions and for your dog's care - confirm anything that matters with a licensed veterinarian or another qualified professional before you act on it. Full disclaimer.
Insurance claim patterns vary sharply between breeds, and a Mastiff's profile is weighted toward a small number of very large, often long-running claims. Bloat surgery, orthopaedic disease, cancer and cardiac care dominate, and every one of them costs more in a dog weighing 120 to 250 pounds because treatment is dosed and equipped by size. The practical consequence is that policy structure matters more than premium.
Most Mastiff owners will make some claim during the dog's nine-to-eleven-year life, and a meaningful proportion will face at least one bill running into thousands. Insurers consistently place giant breeds in their highest pricing bands, which reflects real claims data rather than caution.
The Mastiff's documented health issues read like a list of expensive claim categories: hip dysplasia, elbow dysplasia, cancer, bloat, heart disease, dilated cardiomyopathy and arthritis. Size then multiplies each of them. A dog of 120 to 250 pounds needs more anaesthetic agent, larger implants, longer surgical time, bigger hospital accommodation and more staff to handle safely. The breed's short nine-to-eleven-year lifespan also compresses those claims into fewer policy years, which raises the annual expected cost.
The main non-medical driver is owner decision-making. When cover is taken out, what limit is chosen, whether the policy is lifetime, and whether the annual limit is checked against giant-breed prices all shape whether insurance actually works when it is needed. Geography matters too, since referral hospital pricing varies widely, and a household without access to a practice equipped for giant breeds may face travel and referral costs on top. Lapsing a policy for a year and restarting it is one of the most costly avoidable mistakes, because everything diagnosed in the meantime becomes pre-existing.
Talk to your vet about which preventive measures make sense for a giant breed before you need them, particularly gastropexy at the time of any other planned abdominal procedure, since bloat is the single most expensive emergency this breed faces. Ask for clear, specific wording in the clinical record rather than vague observations, and ask what a referral would cost locally. Seek immediate emergency care, regardless of any insurance question, for a distended or hard abdomen with unproductive retching, collapse, laboured breathing at rest, or an inability to stand. Insurance paperwork is never a reason to delay treatment, and no insurer expects it to be.
See all Mastiff health problems, which breeds are prone to insurance claims, or the full Mastiff breed guide for temperament, exercise needs and ownership costs.
Expect to shop for cover once, properly, and then stay with it. Waiting periods of a couple of weeks are standard at the start, and injury cover often begins sooner than illness cover. Premiums rise as your Mastiff ages, sometimes steeply in the last few years, and switching insurers at that point is usually a bad idea because existing conditions will be excluded by the new policy. Budget for that increase rather than being surprised by it.
Success is that when the large bill arrives, the decision in front of you is medical rather than financial. It is not the absence of claims. A policy that has been in place continuously since puppyhood, with a limit large enough to absorb a giant-breed emergency and cover that renews each year, is doing its job even in the years nothing happens.
Claim patterns follow a breed's documented health issues and its size. For this breed both point in the same expensive direction.
The cheapest premium is rarely the right choice for a Mastiff, because the failure mode is not a small bill you cannot afford but a large one your policy stops covering partway through.
Pay attention to how the cover renews. Policies that cover a condition only for twelve months from first diagnosis, or that reset a per-condition limit permanently once used, are poorly matched to arthritis, cardiac disease and cancer, all of which run for years in this breed. Lifetime cover that reinstates the annual limit at each renewal is the structure that matches the risk, and it is priced accordingly.
Look hard at the annual limit against real giant-breed numbers. A limit that comfortably covers a Labrador's year can be exhausted by one emergency abdominal surgery plus a course of follow-up care in a dog this size.
Check the exclusion wording on hereditary and congenital conditions, and read it specifically for joint disease. Some policies exclude hip dysplasia outright, some cover it, and some cover it only if the dog was insured before a certain age and has never had it noted.
Finally, understand the pre-existing rule. Anything recorded in your dog's clinical history before cover starts, including a passing mention of stiffness or a murmur heard once, can be excluded. This is the strongest argument for insuring a Mastiff from the day you bring the puppy home rather than after the first thing goes wrong.

Hal insured his Mastiff, Peregrine, at eleven months. It felt late but not unreasonable, and he had chosen a competitively priced lifetime policy. What he had not considered was the note from Peregrine's sixteen-week vaccination visit, where a locum had written that a soft murmur was heard and would be rechecked. It was rechecked at six months and had gone. Hal had forgotten about it entirely. When Peregrine was diagnosed with a cardiac condition at seven, the insurer requested his full history, found the puppy note, and declined the cardiac claim as pre-existing. The orthopaedic claim he made the following year was paid without issue. Hal's advice to anyone buying a Mastiff puppy is blunt: arrange the policy before the first appointment, and read every line your vet writes.
Key takeaway: In a breed where the expensive conditions arrive years after the paperwork, the clinical record written in puppyhood is the document that decides what gets paid. Insuring before the first vet visit costs nothing extra and closes a gap that cannot be closed later.
Two reasons compound. The breed's documented health issues skew toward costly categories — bloat, joint disease, cardiac disease and cancer. And body weight inflates the price of almost every treatment, since drugs, anaesthesia and hospitalisation all scale with size. Insurers price both, which is why giant breeds sit in the highest bands.
As early as you reasonably can, before any clinical notes accumulate. A murmur heard at a puppy check, a note about a wobbly gait, or an episode of loose stools can all become the basis of an exclusion later. Cover taken before the first vet visit is cleaner than cover taken after it.
Generally anything that showed signs, was noted, or was treated before your policy began or during any waiting period, whether or not it was formally diagnosed. Insurers request full clinical history when a claim is made, so an informal note from years earlier can surface. Assume everything in the file is visible.
For a giant breed it is the single feature most worth paying for. Emergency abdominal surgery alone can consume a modest annual limit, leaving nothing for the rest of the year in a dog whose other documented risks are also expensive. Judge limits against giant-breed costs, not average dog costs.
It is a legitimate strategy but a demanding one here, because this breed's risks are lumpy rather than gradual. A savings account works well if the bills arrive slowly and badly if a five-figure emergency arrives in year two. If you take this route, fund it seriously and early, and do not treat the balance as available for anything else.
Yes, substantially, and insurers have far better data on this than owners do. Different breeds show consistently different claim rates for specific conditions, which is why breed is one of the strongest inputs into pricing. For a Mastiff, expect a profile weighted toward fewer, larger, longer-running claims.
Their documented risks skew toward expensive categories such as bloat surgery, joint disease, cardiac care and cancer, and body weight inflates the price of every drug and procedure.
Before the first vet visit if possible. Notes in the clinical record, even informal ones, can become permanent exclusions later.
A high annual limit that reinstates each year. One emergency abdominal surgery can exhaust a modest limit in a dog this size.
It varies by policy. Some exclude hereditary joint conditions outright, others cover them subject to age and clean history. Read that clause specifically before buying.
You can usually get a policy, but that condition and anything related to it will normally be excluded permanently. Cover bought after a diagnosis protects only against what has not happened yet.
A one-page prep sheet for this condition: the signs, the questions to ask, what to get priced. Unlocks here.
You get: Vet visit prep sheet
No spam. One-click unsubscribe. See our privacy policy.
See a sample page before you decide.
Early access list
The free prep sheet covers the same-day warning signs, a symptom log and the questions to ask. We are considering a fuller kit that adds a cost worksheet for the usual tests and treatments (US price ranges with their sources) and a plain-English guide to ways of covering the bill. It is not built yet; this list tells us whether it is worth building.
One email, no spam, unsubscribe anytime. Information only, not veterinary advice.