Costs
What do Bichon Frise owners claim for most?
Skin and ear problems, urinary stones, kneecap issues and eye disease reflect the breed's documented health profile.
Quick answer
What do Bichon Frise owners claim for most?
Skin and ear problems, urinary stones, kneecap issues and eye disease reflect the breed's documented health profile.
Claim data does not tell you what your breed suffers from. It tells you what insured owners of that breed were willing to spend money on, which is a different question.
New owners choosing a policy and trying to work out what level of cover a Bichon actually needs, and existing owners who have just discovered that the thing they claimed for is excluded.
This guide is not medical advice. If your dog shows pain, sudden behavior change, or worsening symptoms, consult a licensed veterinarian.
Some links may be affiliate links. We may earn a commission at no extra cost to you. We only suggest products we believe are helpful for dog owners.
We research and check what we publish, but we do not warrant that any figure, date, price, or statement is accurate, complete, or current, and we accept no liability for any loss, cost, injury, or other harm arising from the use of this site. Use it as one reference among several. You remain responsible for your own decisions and for your dog's care - confirm anything that matters with a licensed veterinarian or another qualified professional before you act on it. Full disclaimer.
The problem here is financial rather than clinical, and it has two halves. The first is interpreting breed claim data honestly instead of treating it as a disease register. The second is choosing and maintaining cover that actually matches how a Bichon's health costs arrive, which is as a long chronic drip in the skin and a small number of large one-off surgical events.
Disputes about what is covered are far more common than outright refusals to pay. The recurring themes across breeds are pre-existing exclusions, per-condition caps and definitional arguments about diets and dentistry. A Bichon's health profile happens to touch all three, which makes reading the policy unusually worthwhile for this breed.
The Bichon's documented conditions divide neatly into two cost shapes. Skin allergies and dental disease are chronic and recurring, so they interact with annual per-condition limits. Bladder stones, cataracts and kneecap surgery are episodic and expensive, so they interact with overall limits and excesses. A lifespan of 14 to 15 years means an owner experiences both shapes across a long period during which premiums are also climbing.
Where you live changes the numbers more than most owners expect, since veterinary fees and referral availability vary widely by region. The other environmental factor is timing: cover arranged in the first weeks of ownership behaves completely differently from cover arranged after a puppy has already been seen for an itchy ear. Households that switch insurers to chase a cheaper premium also reset their exclusion position.
Never let a coverage question delay care. Go the same day for straining to urinate or producing no urine, collapse, breathing difficulty, repeated vomiting, or a sudden inability to bear weight, and sort the paperwork afterwards. Book routinely for recurring itching, ear discharge, a limp lasting more than two days, or eye cloudiness. If cost is genuinely the barrier, say so at the practice rather than waiting; most will discuss staged investigation or payment options.
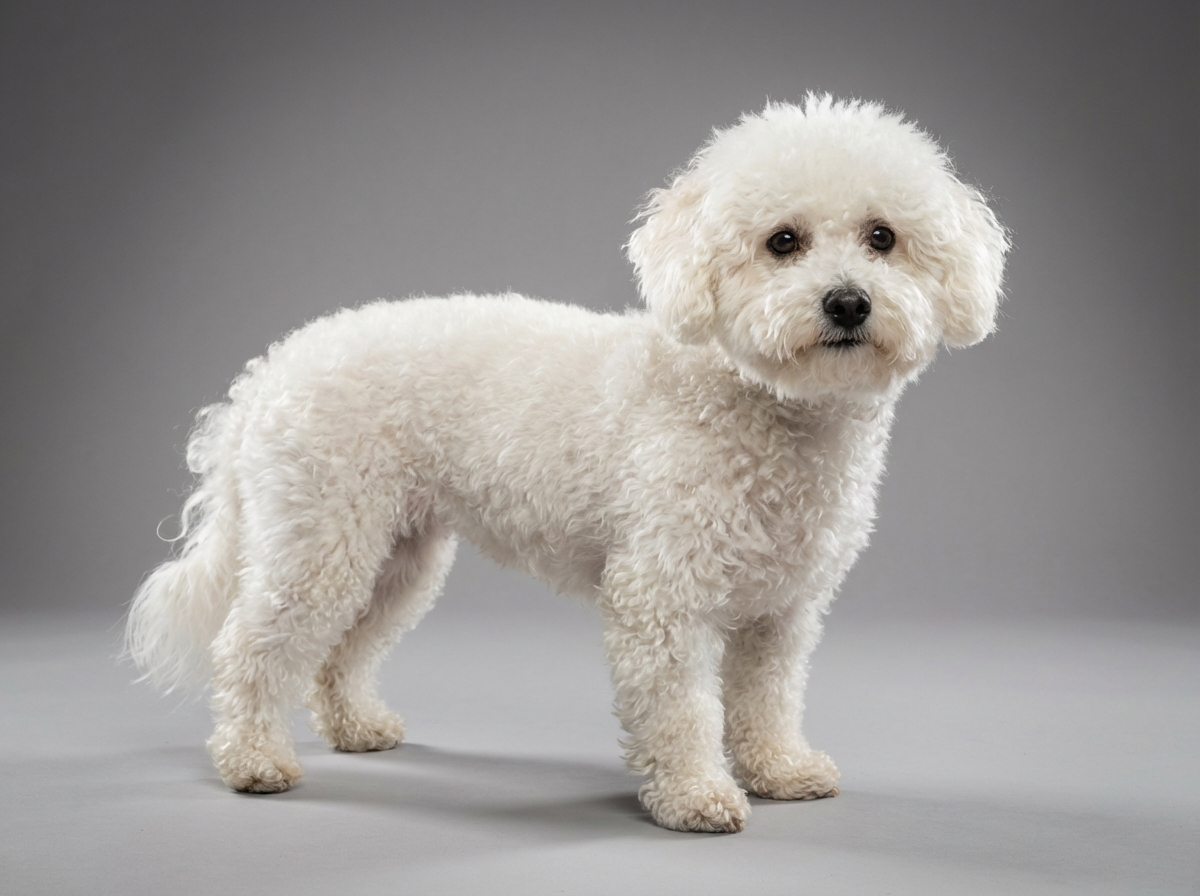
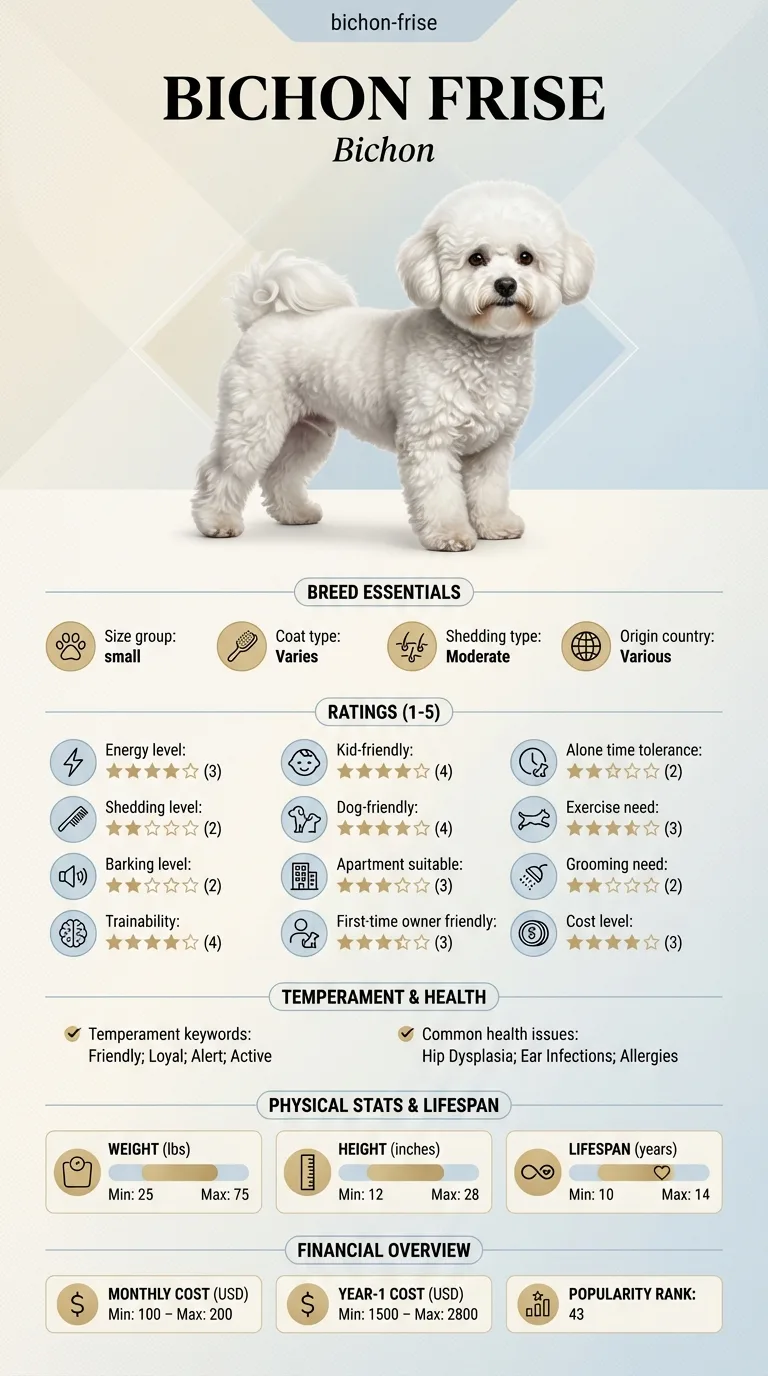
See all Bichon Frise health problems, which breeds are prone to insurance claims, or the full Bichon Frise breed guide for temperament, exercise needs and ownership costs.
Waiting periods typically run from days for accidents to weeks or months for illness and orthopaedic conditions. Individual claims are commonly settled within a couple of weeks. The meaningful timeline, though, is the fourteen-year one: the decisions you make in month one determine what is claimable in year ten.
You know your policy's per-condition cap, your excess, and which of your breed's likely conditions are excluded. Nothing your dog has ever been seen for is a surprise exclusion, and you have a separate fund for dentistry. Success is never having to weigh a diagnostic test against a bill.
Rather than repeating a generic top-ten list, it is more useful to work from the conditions this breed is actually documented for, and think about how each behaves as a claim.
Most policy disappointment comes from three mechanisms, and each one interacts badly with the Bichon's particular health profile.
The first is per-condition limits. A lifetime policy with a generous overall figure can still cap a single condition at a modest annual amount. For chronic skin allergy, which is managed for years rather than cured, that cap is the number that actually governs your experience, not the headline.
The second is the pre-existing exclusion, applied to anything noted in the clinical record before cover began or during the waiting period. A murmur mentioned in passing, an ear infection at eight months, or a patella described as slightly loose at a puppy check can all become permanent exclusions. This is why arranging cover before the first vet visit, rather than after, changes what you can claim for over a fourteen-year life.
The third is the definition of treatment. Prescription diets, dental work, behavioural consultations and grooming-adjacent care are handled inconsistently between insurers, and a Bichon is a breed likely to need several of them.

Nadia insured her Bichon puppy, Milo, at four months. She had taken him to the vet at ten weeks for a mildly smelly ear, which was cleaned and resolved in a week and which she had entirely forgotten. At three, Milo developed persistent itching and recurring ear inflammation. The insurer reviewed his history, found the ten-week note, and applied an exclusion for ear and associated skin conditions. The cost of managing his allergies came out of pocket for the rest of his life. Nadia's assessment afterwards was that the policy was not unfair, only that she had bought it two months too late.
Key takeaway: In a breed prone to early minor skin and ear notes, the day you arrange cover matters more than the insurer you choose. Buy before the first appointment, not after.
Only loosely. They reflect insured dogs whose owners claimed, so conditions that are expensive and obvious dominate while cheap or slow-burning ones vanish. Two insurers can publish different breed rankings from the same year because their customer bases and policy terms differ.
That is a budgeting judgement rather than a medical one. The relevant facts are that this breed commonly lives 14 to 15 years and has documented chronic conditions in skin and urinary tract. Long life plus chronic conditions is the profile where lifetime cover tends to earn its cost, though not in every case.
Before the first veterinary examination if possible, and certainly before any minor issue is recorded. Waiting periods and pre-existing exclusions are assessed against the clinical history, and this breed accumulates notes about skin, ears and knees early.
Usually yes under a lifetime policy, provided nothing was recorded before cover started, but check the per-condition annual limit carefully. Allergy management runs for years, and it is the recurring nature rather than any single bill that tests a policy.
Age is the main driver, and it rises steeply through the second half of a long-lived breed's life. Claims history and regional vet costs also feed in. Switching insurer at that point usually re-triggers exclusions for anything already claimed, which is the trap.
Frequently not, or only when preceded by documented annual dental examinations. Given that dental disease is on this breed's core list, read that section before buying rather than after your vet recommends a procedure.
Skin and ear problems, urinary stones, kneecap issues and eye disease reflect the breed's documented health profile.
Lifetime cover renews the limit for ongoing conditions each year. Annual cover stops paying once a condition has run its twelve months.
Often yes, but new policies for senior dogs carry higher premiums, higher excesses and broad exclusions for anything already recorded.
It should make you more willing to investigate early rather than wait, which is usually cheaper and better for the dog.
Sometimes, under a referral clause. For a breed with low alone-time tolerance this is worth checking before you need it.
A one-page prep sheet for this condition: the signs, the questions to ask, what to get priced. Unlocks here.
You get: Vet visit prep sheet
No spam. One-click unsubscribe. See our privacy policy.
Preview page 1 before you decide.