Costs
What do German Shorthaired Pointers most often claim for?
Traumatic wounds and foreign bodies from field activity, orthopaedic problems including hip and elbow dysplasia, ear disease, and occasional high-value gastric emergencies.
Quick answer
What do German Shorthaired Pointers most often claim for?
Traumatic wounds and foreign bodies from field activity, orthopaedic problems including hip and elbow dysplasia, ear disease, and occasional high-value gastric emergencies.
The costliest thing most GSP owners do to their insurance is nothing at all: they wait until something is noticed before they buy the policy.
New owners comparing policies before a puppy comes home, people whose claim was declined on a pre-existing basis and did not see it coming, and owners of working dogs trying to work out whether field injuries are actually covered.
This guide is not medical advice. If your dog shows pain, sudden behavior change, or worsening symptoms, consult a licensed veterinarian.
Some links may be affiliate links. We may earn a commission at no extra cost to you. We only suggest products we believe are helpful for dog owners.
We research and check what we publish, but we do not warrant that any figure, date, price, or statement is accurate, complete, or current, and we accept no liability for any loss, cost, injury, or other harm arising from the use of this site. Use it as one reference among several. You remain responsible for your own decisions and for your dog's care - confirm anything that matters with a licensed veterinarian or another qualified professional before you act on it. Full disclaimer.
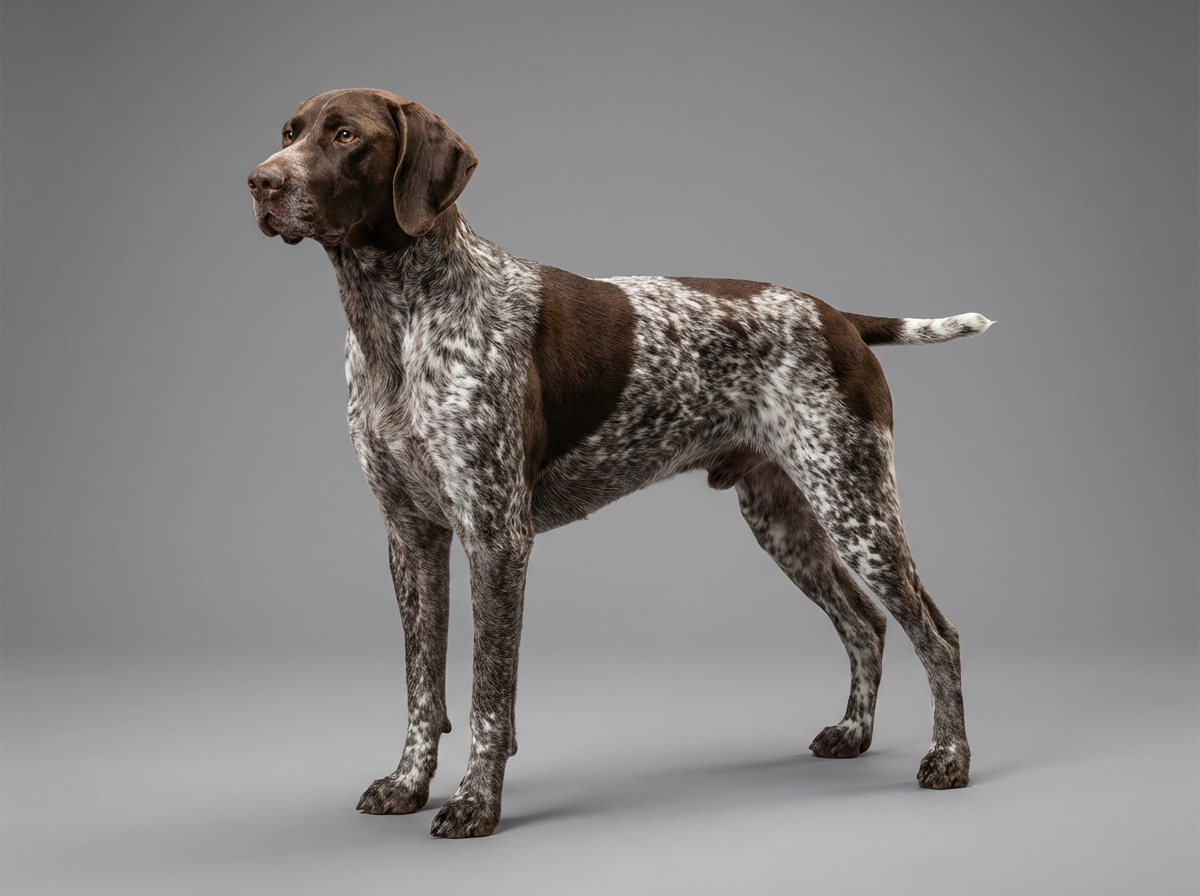
Claim patterns differ between breeds because breeds differ in anatomy, documented conditions and lifestyle. The German Shorthaired Pointer's file skews toward the consequences of hard outdoor work, with wounds, embedded plant material and joint injuries alongside the breed's documented conditions such as hip and elbow dysplasia, bloat and recurring ear infections. The recurring financial problem for owners is not the claim itself but the pre-existing exclusion that quietly removed the cover beforehand.
Claiming at some point across a 10 to 12 year lifespan is more likely than not for a working German Shorthaired Pointer, though most claims are modest rather than catastrophic. Small repeated claims for ears, skin and minor wounds are the everyday reality; large single claims for gastric emergencies or orthopaedic surgery are uncommon but are the reason insurance exists at all.
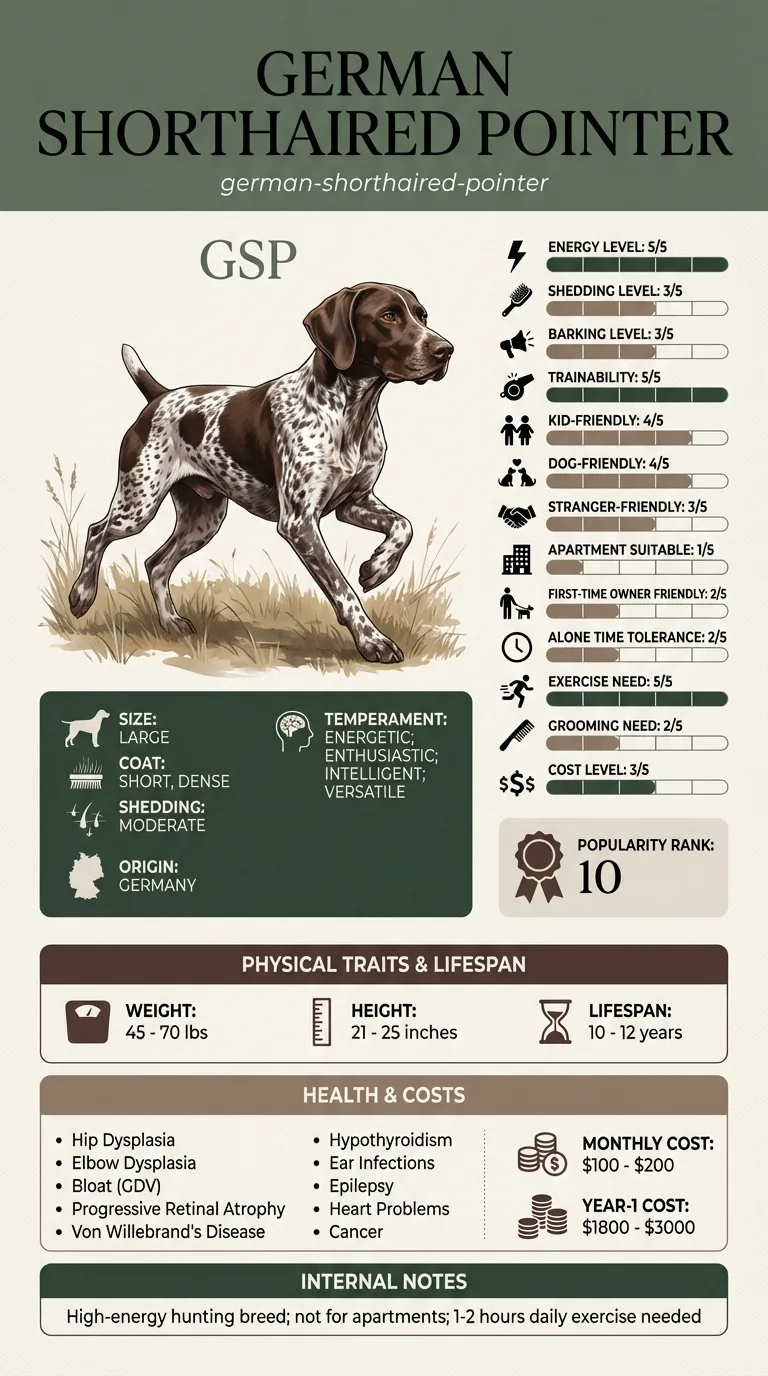
The breed record explains most of the pattern. Energy and exercise need are rated five out of five with one to two hours of daily work required, so exposure to injury is high simply by hours spent in rough terrain. Adult size of 45 to 70 pounds and 21 to 25 inches places the dog in the band where joint disease becomes clinically expensive, and hip and elbow dysplasia head its documented health list. Bloat appears on the same list, and a deep-chested large breed generates the occasional very large emergency claim. Chronic ear infections contribute a steady stream of smaller ones.
How the dog is kept matters as much as what it is. A GSP used as a working gun dog in dense cover accumulates trauma claims that an urban companion never will, and that same dog may fall under working-activity restrictions in some policies. Rural owners may be further from an emergency facility, which changes both outcome and cost. Owners who insure late, or who move providers chasing a lower premium, systematically end up with narrower cover than their premium history suggests.
Insurance is administrative, but the underlying events are not. Seek emergency care immediately for a distended, tight abdomen with unproductive retching and restlessness, which is a gastric emergency and needs surgery within hours. Go the same day for deep wounds, penetrating eye injuries, sudden non-weight-bearing lameness, or a dog that has been staked or gored in cover. Book promptly for a grass seed suspected in an ear, a nose or between the toes, since these migrate and become considerably harder to retrieve with time. Never delay treatment while sorting out a claim; document afterwards.
See all German Shorthaired Pointer health problems, which breeds are prone to insurance claims, or the full German Shorthaired Pointer breed guide for temperament, exercise needs and ownership costs.
Most policies impose short waiting periods before cover begins, typically days for illness and sometimes longer for certain conditions, so cover is not instant. Claims are usually settled within weeks provided the clinical history is complete. Over a dog's life, expect premiums to rise steadily with age and to increase noticeably in the senior years, which is a normal feature rather than a sign of a bad provider.
Success is a policy bought early, kept continuously with the same insurer, whose wording you have actually read, and which still covers a chronic condition in year eight because you never switched. It also looks like a claim file dominated by small preventable-adjacent events rather than emergencies. It does not look like the cheapest monthly premium, which is usually the least useful thing to optimise.
Claim patterns follow from breed traits, and this breed's traits point in fairly specific directions.
Almost every policy excludes conditions that existed before cover began, and the definition of existed is broader than owners expect. It does not require a diagnosis. A note in the clinical record is usually enough.
That is why a soft heart murmur mentioned at a routine visit, a single episode of limping written down at eighteen months, or an itchy ear recorded once as a puppy can quietly close off a whole category of future claims. None of those felt like a medical event at the time.
The same logic explains why insuring at the point of purchase, before the first adult examination, is worth so much more than insuring at a convenient later date. You are buying cover while the file is still empty.
A second version of this trap catches owners who switch insurers to save money. Anything recorded during the first policy becomes pre-existing for the new one. Moving providers after a few years of ownership can therefore cost far more than the premium difference saves, and this is the single most common expensive mistake in the whole subject.

Wanda insured her GSP, Tilly, at four months old, three weeks after bringing her home. In that gap Tilly had a routine health check where the vet noted mild redness in one ear and dispensed a cleaner. Nobody thought about it again. At three years old Tilly developed severe recurrent ear disease that eventually needed specialist management. The claim was declined as pre-existing, on the basis of that one line in a puppy record. Wanda appealed, produced the original consultation notes hoping they would show it was trivial, and lost. The insurer's position was that ear disease had been recorded before cover started, and it had. She now tells every new GSP owner she meets to buy the policy in the car park on the way home from the breeder.
Key takeaway: Pre-existing does not mean diagnosed. It means written down. The cheapest hour in a GSP's insurance history is the hour before its first veterinary appointment.
They sit in a middle band rather than at the extremes. Premiums reflect adult size, documented conditions such as hip dysplasia and bloat, and a lifestyle that generates trauma claims. The breed record puts general running costs at roughly 100 to 200 dollars a month, and insurance is a meaningful line within that.
This varies genuinely between providers, and it is one of the few things worth reading the policy wording for rather than the summary. Some policies restrict or exclude injuries arising from working activity or organised sport. If your GSP will actually be used as a gun dog, confirm the position in writing before you need to.
An annual policy typically stops covering a condition at the end of the policy year, after which it becomes pre-existing. A lifetime policy continues covering it year after year up to a limit that refreshes. For chronic conditions such as thyroid disease, allergies or arthritis, that difference is the whole point of insuring.
Immediately, ideally the day you take the puppy home. Waiting until after the first examination is precisely when a murmur, a hernia or a skin note can be recorded and then permanently excluded. A few days of delay is genuinely capable of costing thousands later.
Premiums generally rise with the dog's age regardless, and a claim history can add to that. What is more consequential than the premium increase is the condition-specific exclusion or limit that can follow, so read the renewal terms carefully rather than only checking the monthly figure.
It can be, though options narrow with age and some providers will not start new cover past a certain point. Run the numbers honestly against a dedicated savings account, particularly for a dog well into a 10 to 12 year lifespan, and be clear that anything already in the record will be excluded from the outset.
Traumatic wounds and foreign bodies from field activity, orthopaedic problems including hip and elbow dysplasia, ear disease, and occasional high-value gastric emergencies.
The day the puppy comes home, before the first veterinary examination adds anything to the clinical record that could later count as pre-existing.
Once documented, it typically becomes a pre-existing condition and can exclude later cardiac claims, which is a strong argument for insuring early.
Be careful. Everything recorded under the old policy becomes pre-existing under the new one, so the saving can be far smaller than the cover you give up.
Not automatically. Some policies limit or exclude injuries from working activity, so confirm the wording in writing if your dog will actually be worked.
A one-page prep sheet for this condition: the signs, the questions to ask, what to get priced. Unlocks here.
You get: Vet visit prep sheet
No spam. One-click unsubscribe. See our privacy policy.
Preview page 1 before you decide.