Costs
What type of pet insurance suits a Chow Chow?
Lifetime cover with a high annual limit. The breed's documented conditions are mostly lifelong, so time-limited or per-condition-capped policies fail exactly when needed.
Quick answer
What type of pet insurance suits a Chow Chow?
Lifetime cover with a high annual limit. The breed's documented conditions are mostly lifelong, so time-limited or per-condition-capped policies fail exactly when needed.
The claim that gets refused is almost never the one you expected. It is the one your vet noted in passing eleven months before you bought the policy.
New Chow owners choosing a first policy, owners whose claim has been declined and who want to understand why, and anyone renewing a policy on a dog who has just been diagnosed with something.
This guide is not medical advice. If your dog shows pain, sudden behavior change, or worsening symptoms, consult a licensed veterinarian.
Some links may be affiliate links. We may earn a commission at no extra cost to you. We only suggest products we believe are helpful for dog owners.
We research and check what we publish, but we do not warrant that any figure, date, price, or statement is accurate, complete, or current, and we accept no liability for any loss, cost, injury, or other harm arising from the use of this site. Use it as one reference among several. You remain responsible for your own decisions and for your dog's care - confirm anything that matters with a licensed veterinarian or another qualified professional before you act on it. Full disclaimer.
Insurance problems for Chow Chow owners cluster around two moments: choosing a policy that will still be useful in year eight, and discovering at claim time that a condition was already on the record. Because this breed's documented issues are disproportionately chronic, bilateral and surgical, the ordinary shortcuts of policy shopping fail more expensively here than they do for most dogs.
Claim patterns vary by breed because health risks do. For the Chow the recurring themes are orthopaedic surgery, ophthalmic procedures, endocrine management and emergency gastric surgery, all of which map directly onto the ten health issues documented for the breed rather than onto anything random.
The Chow's documented problems are structurally bad news for insurance. Hip and elbow dysplasia are congenital in origin, bilateral by nature and expensive to treat surgically. Entropion and distichiasis are eyelid conformation problems visible in puppyhood, which is precisely when a pre-existing note gets written. Thyroid disease and diabetes are permanent management conditions. Bloat is a sudden, high-cost surgical emergency associated with a deep-chested build. Cataracts and glaucoma add referral-level ophthalmology. Very few breeds concentrate so many expensive categories on one list, and insurers price accordingly.
How and when you buy matters as much as the breed. Buying after adoption of an adult rescue means the medical history is unknown but the exclusions are real. Switching insurers to chase a cheaper renewal quote resets everything already diagnosed into the pre-existing category, which is why so many owners of chronically ill dogs stay with an expensive insurer. Regional veterinary pricing changes what an annual limit is actually worth, and a limit that is generous in one area is thin in another.
Insurance should never delay care, and this breed has emergencies where minutes matter. Go immediately, and sort out the paperwork afterwards, for a swollen or hard abdomen with unproductive retching, collapse, laboured breathing, a suddenly painful or cloudy eye, or an inability to stand. Bloat and acute glaucoma are both on this breed's risk profile and both cause permanent harm within hours. For non-urgent matters, ask your vet's practice manager how they handle direct claims, since some clinics will bill an insurer directly and that changes the cash flow of a large claim considerably. Also ask for a written clinical summary after any significant diagnosis, because you will need it for every future policy conversation.
See all Chow Chow health problems, which breeds are prone to insurance claims, or the full Chow Chow breed guide for temperament, exercise needs and ownership costs.
Most policies impose a waiting period of a few days for accidents and around two weeks for illness, so cover is never instant. Claims are typically settled within two to four weeks with complete documentation, and much longer without it. Premiums rise annually and rise sharply after about age eight in most breeds.
Success is boring: a lifetime policy bought early, never switched, with a limit that survives a surgical year, and a folder of records that makes each claim a formality rather than an argument.
Every one of these is legal, disclosed in the policy wording, and predictable. None of them is discovered at a convenient moment.
Buy lifetime cover, not time-limited or per-condition-capped cover. The Chow's documented list is dominated by conditions that never resolve: thyroid disease is lifelong, diabetes is lifelong, arthritis following dysplasia is lifelong, and glaucoma requires ongoing management. A policy that covers each condition for twelve months is close to useless against that list, and it is usually the cheapest quote on any comparison site for exactly that reason.
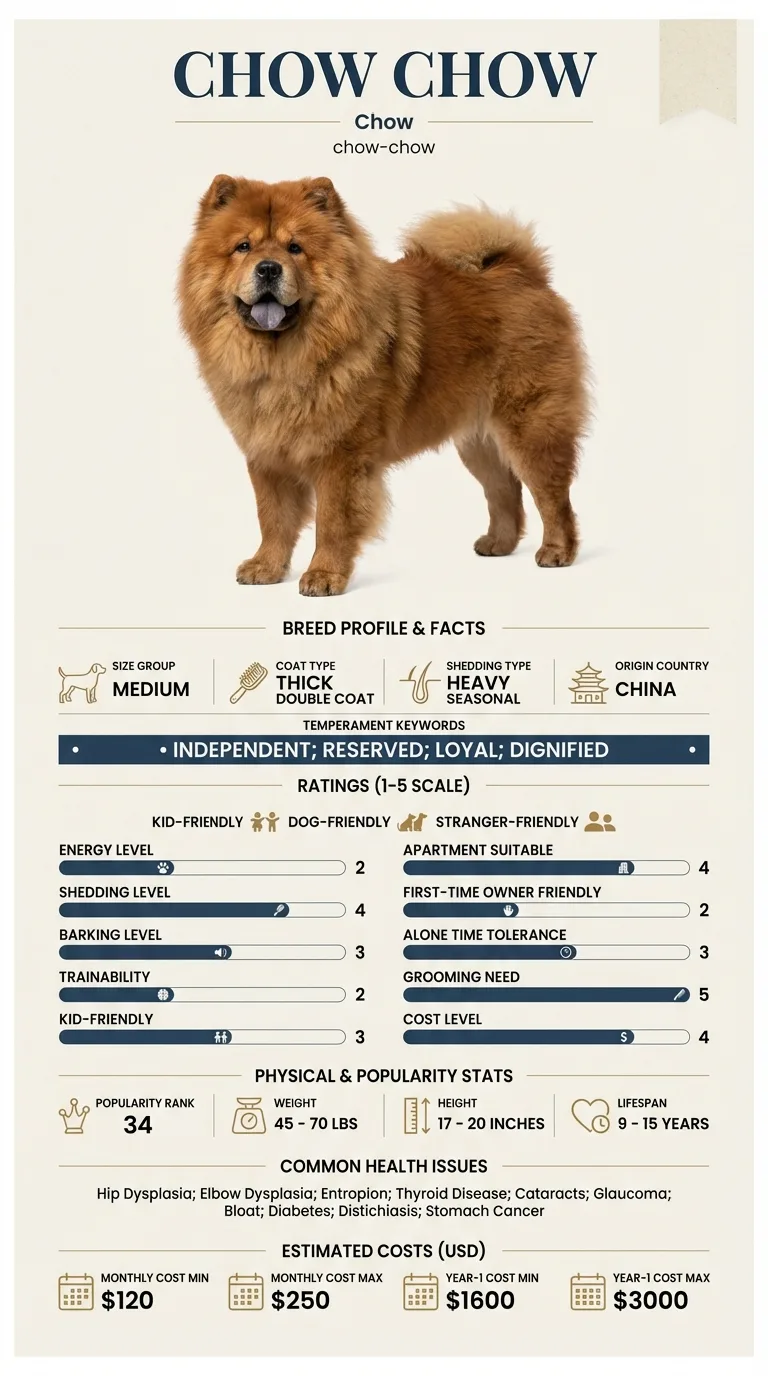
Set the annual limit against surgical reality rather than routine spending. This breed's ordinary running cost sits at roughly 120 to 250 dollars a month, but that is the number insurance is not for. Insurance is for the year with a hip replacement, an emergency bloat surgery, a glaucoma referral and a course of rehabilitation, and those can occur in the same twelve months.
Insure early and insure before the first vet visit if you can, because the pre-existing clock starts with clinical notes, not with diagnosis. A breeder handing over a puppy at eight weeks is handing over the last moment when the record is genuinely clean.
Finally, read the exclusions list specifically for hereditary and congenital conditions. Some policies exclude conditions typical of the breed by name. For a Chow that could mean hips, elbows and eyelid disease, which is most of what you were buying insurance to cover.

Otis was insured at fourteen months, which his owner Raj thought was early. The policy was a good lifetime product with a generous limit. At three, Otis needed surgical correction of entropion on both lower eyelids. The claim was declined. The insurer had requested his full clinical history and found a line from his eight-week health check: eyes slightly watery, monitor. Nobody had diagnosed anything. The note was enough. Raj appealed and lost, then paid for the surgery himself. He now insures from the day of collection and asks the breeder's vet for a copy of the health-check notes before signing anything.
Key takeaway: Exclusions are built from clinical notes, not diagnoses. In a breed where eyelid conformation is documented, the first eleven weeks of a dog's record can decide what you can ever claim for.
Generally yes, relative to a similarly sized breed with a shorter health list. Premiums reflect claim history, and this breed's documented issues include several conditions that generate large surgical and lifelong claims. The breed also carries a cost rating of 4 out of 5 overall.
You can usually get a policy, but not one that covers the hips. Expect that condition, often both sides, to be excluded permanently. Cover for unrelated illness and accidents is still worth having, particularly given bloat risk.
It means that if a paired structure was affected on one side before cover started, the other side is excluded too. For a breed whose documented issues include hip dysplasia, elbow dysplasia, entropion and cataracts, all of which are paired, this clause has unusually wide reach.
Emergency gastric surgery is normally covered by a standard illness policy provided the condition was not pre-existing, and this is one of the strongest arguments for insuring a Chow at all. Preventive gastropexy performed electively is often treated as prophylactic and declined, so ask before booking one.
Self-insuring works only if you would genuinely have the full sum available on the day. A single bloat surgery or hip replacement can exceed several years of premiums, and it arrives without notice. If you self-insure, the money needs to be untouched and liquid, not theoretical.
It is worth checking. Some home and pet policies restrict or exclude certain breeds from liability cover, and the Chow appears on some of those lists. Given ratings of 2 out of 5 for dog friendliness and stranger friendliness, confirm the liability section explicitly rather than assuming.
Lifetime cover with a high annual limit. The breed's documented conditions are mostly lifelong, so time-limited or per-condition-capped policies fail exactly when needed.
Before the first veterinary appointment if possible. Pre-existing exclusions are triggered by clinical notes, not by formal diagnosis.
Hips, elbows and eyelid conditions such as entropion, because they are documented in the breed and often noted in records early.
Usually not, because elective preventive surgery is commonly excluded. Emergency bloat surgery generally is covered. Ask your insurer in writing before booking.
A one-page prep sheet for this condition: the signs, the questions to ask, what to get priced. Unlocks here.
You get: Vet visit prep sheet
No spam. One-click unsubscribe. See our privacy policy.
Preview page 1 before you decide.