Costs
When should cover start?
In the first days of ownership, ideally before any veterinary examination has written anything into the record.
Quick answer
When should cover start?
In the first days of ownership, ideally before any veterinary examination has written anything into the record.
The claim that ruins a family financially is almost never the one they were worried about when they bought the policy.
For prospective and new Newfoundland owners comparing policies, and for existing owners trying to work out whether their current cover would actually pay for the things this breed is most likely to need.
This guide is not medical advice. If your dog shows pain, sudden behavior change, or worsening symptoms, consult a licensed veterinarian.
Some links may be affiliate links. We may earn a commission at no extra cost to you. We only suggest products we believe are helpful for dog owners.
We research and check what we publish, but we do not warrant that any figure, date, price, or statement is accurate, complete, or current, and we accept no liability for any loss, cost, injury, or other harm arising from the use of this site. Use it as one reference among several. You remain responsible for your own decisions and for your dog's care - confirm anything that matters with a licensed veterinarian or another qualified professional before you act on it. Full disclaimer.
Insurance claims for a Newfoundland cluster around four areas that follow directly from the breed's documented health profile: orthopaedic disease driven by hip dysplasia in a very heavy dog, emergency gastric surgery for bloat, cardiac care for subaortic stenosis and dilated cardiomyopathy, and urinary stone disease arising from cystinuria. Each behaves differently under different policy structures, which is why the wording matters more than the premium.
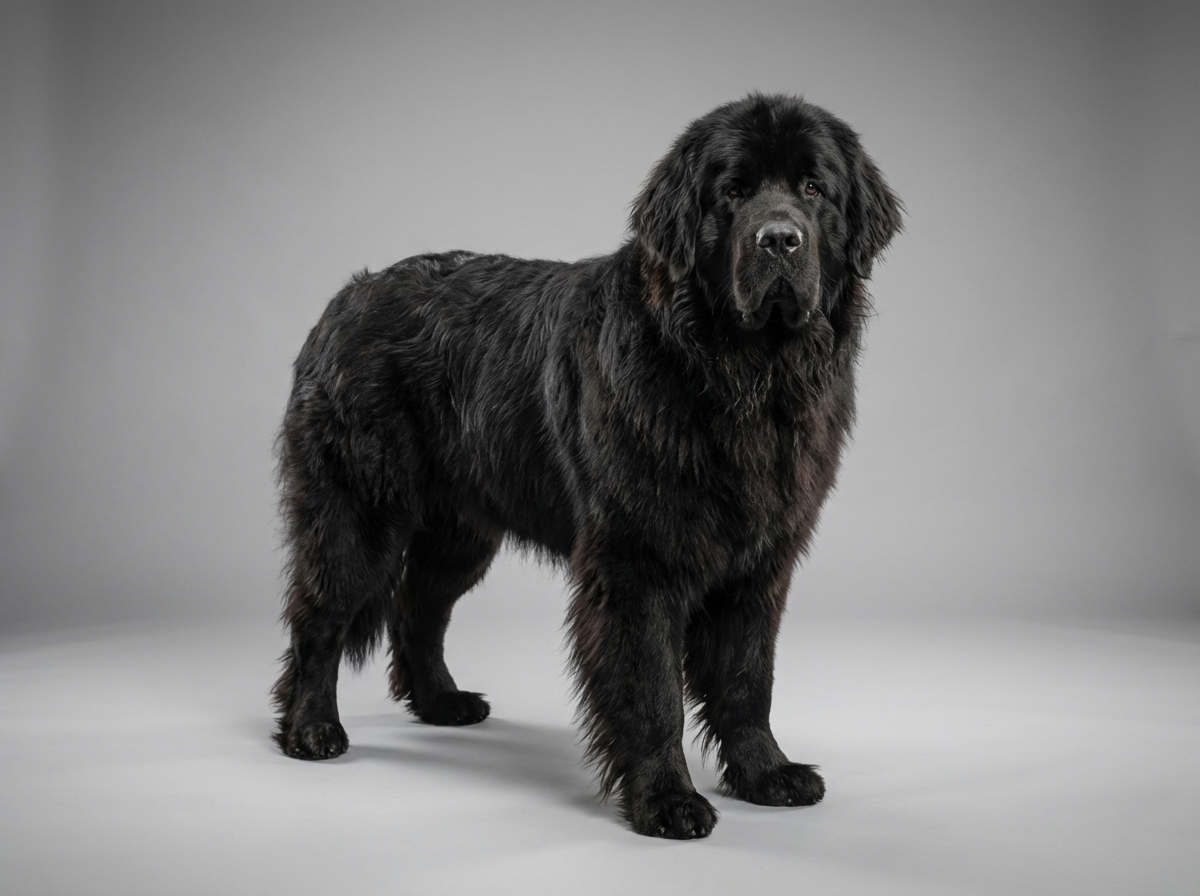
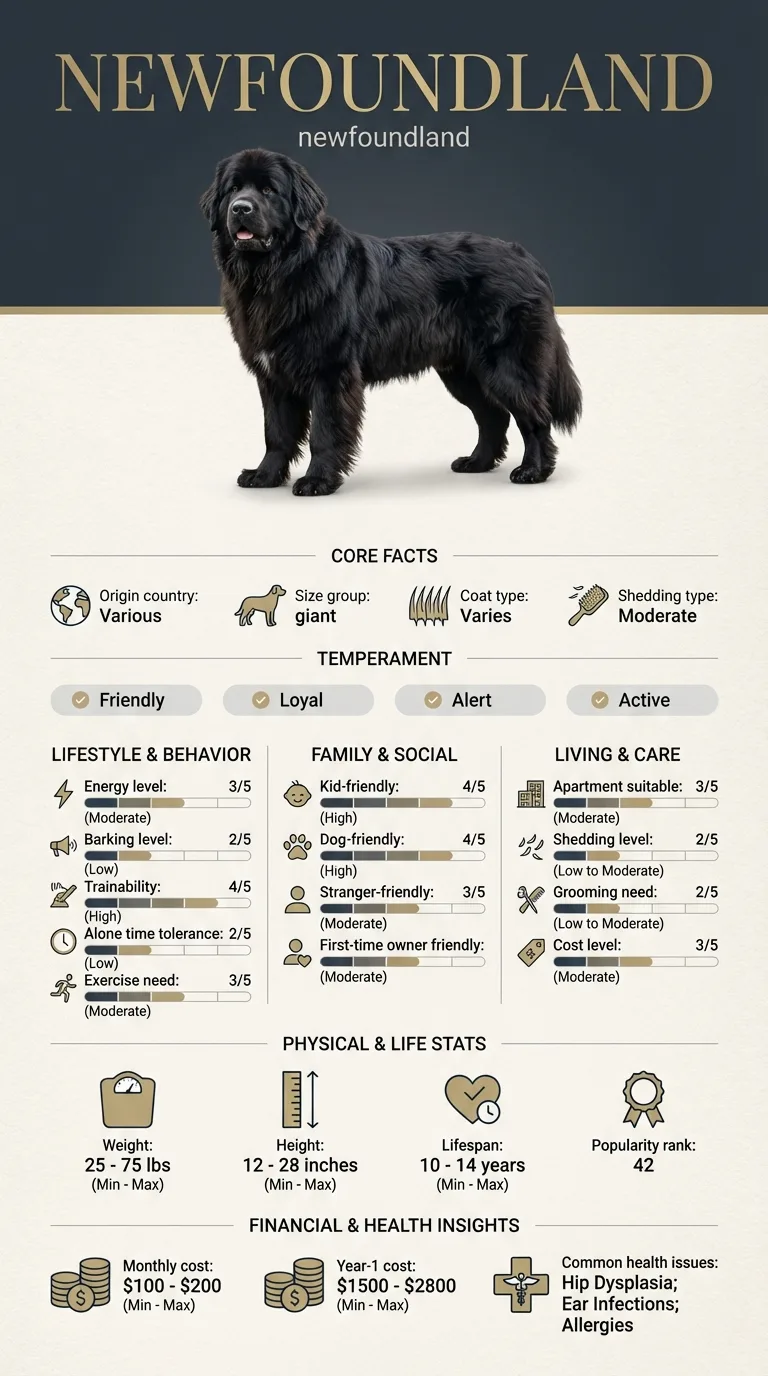
Making claims is normal rather than exceptional for this breed. A giant dog with a nine to ten year lifespan and five documented health predispositions is statistically likely to need significant veterinary care at some point, and the breed already sits in the highest ownership cost tier with monthly costs between 150 and 310 dollars before any illness.
The claim pattern is a direct readout of the breed standard. Hip dysplasia, subaortic stenosis, dilated cardiomyopathy, cystinuria and bloat are the Newfoundland's documented health issues, and every one of them generates expensive, often recurring veterinary work. Body mass amplifies each of them financially: a dog of 100 to 150 pounds needs more anaesthetic agent, larger implants, bigger drug volumes and more hospital space than a small dog receiving identical care. The breed's nine to ten year lifespan compresses those costs into a shorter period than they would occupy in a longer-lived breed, so the annual claim rate looks higher.
Where you live changes the arithmetic substantially, since veterinary pricing, specialist availability and insurance regulation all vary by region. Households far from a referral centre may face transport and out-of-hours costs on top of treatment. Owners in hot climates carry additional heat-related emergency risk. And household habits feed directly into claims, because a dog kept lean on non-slip flooring, fed measured meals rather than one large one, and exercised sensibly in cool conditions simply generates fewer claimable events than one that is not.
Insurance decisions are financial rather than clinical, but the clinical thread matters. Ask your veterinarian to explain exactly what has been written in your dog's record and what it might mean for future cover, particularly after any puppy examination. Seek emergency care without hesitating over cost if your dog shows a swollen or tight abdomen with unproductive retching, collapses, strains to urinate without producing urine, breathes with difficulty at rest, or is suddenly unable to stand. All of those are life-threatening, all of them are claimable, and delaying to check policy wording is the wrong order of priorities.
See all Newfoundland health problems, which breeds are prone to insurance claims, or the full Newfoundland breed guide for temperament, exercise needs and ownership costs.
Cover should be in place within days of bringing a dog home, and waiting periods typically mean nothing is claimable for the first couple of weeks, with orthopaedic conditions often waiting longer than that. Premiums rise as the dog ages, and by the senior years they can be several times the puppy price. Individual claims usually settle within weeks. The overall arc is that early years are cheap and quiet, and the last third of a Newfoundland's life carries most of the claims.
Success is a policy that pays for the thing your dog actually gets, without an argument about whether it was pre-existing. That means cover arranged early, hereditary conditions included, chronic problems still covered in their fifth year, and a household that never has to choose between a treatment and a mortgage payment. Success is not the lowest premium; it is the claim that goes through when a giant dog needs abdominal surgery at two in the morning.
Claims for a Newfoundland do not spread evenly across the medical spectrum. They concentrate in a few expensive areas that follow directly from what this breed is documented to develop.
Orthopaedic work leads. Hip dysplasia is on the breed's health issue list, and joint disease in a dog weighing 100 to 150 pounds generates imaging, long-term pain management, rehabilitation and occasionally major surgery. These are not one-off events but multi-year cost streams.
Emergency abdominal surgery is the sharpest single item. Bloat is documented in this breed and it is a surgical emergency, which means an out-of-hours admission, imaging, anaesthesia, surgery and several days of intensive care. It is one of the few events that can produce a five-figure bill from a dog that was completely well at breakfast.
Cardiac care is the third pillar, since both subaortic stenosis and dilated cardiomyopathy sit on the breed's documented list. Specialist imaging, repeat scans and long-term medication accumulate steadily rather than dramatically.
Urinary disease is the fourth and the one owners rarely anticipate. Cystinuria is documented in the breed, and stone-related obstruction is both an emergency and a recurring problem, which makes it particularly awkward under policies with annual condition limits.

Two policies at the same monthly price can behave completely differently for this breed. The differences hide in clauses rather than in the headline number.
The single most expensive mistake a Newfoundland owner can make is starting cover late. The reason is that this breed's characteristic problems are exactly the ones most likely to be noted early and then excluded.
Consider a murmur. A veterinarian listening to an eight-week-old puppy may note something soft and unremarkable. If insurance is arranged after that visit, the insurer can reasonably treat any subsequent cardiac condition as pre-existing, and cardiac care is one of the categories most likely to be needed. The same logic applies to a puppy noted as having a loose gait, or to a young dog whose urine was flagged as containing crystals.
Hip dysplasia has a related trap. It is a condition that develops silently over years, so a policy taken out at four because the dog is starting to stiffen will very likely exclude it. The cover has to exist before there is a reason to want it.
The practical conclusion is uncomfortable but simple. If insurance is part of your plan for a Newfoundland, arrange it in the first days of ownership, ideally before the first veterinary examination, and be honest on the application. Non-disclosure does not save money; it produces a declined claim at the worst possible moment.
Two families collected Newfoundland puppies from the same litter in the same week. One arranged insurance from the day of collection, before the puppy had been examined by their own veterinarian. The other planned to sort it out after the first vaccination visit, reasoning that they would know more by then. At that visit, both puppies were noted to have a soft murmur, exactly the sort of finding that often means nothing. The first family's policy was already active and the finding sat inside their cover. The second family's application, submitted three days later, produced a policy with a cardiac exclusion attached. At three years old the second dog was diagnosed with a narrowing below the aortic valve. Imaging, specialist consultations and ongoing monitoring have cost the family close to nine thousand dollars so far, none of it claimable. The first dog's murmur, incidentally, faded by four months and has never needed a thing.
Key takeaway: In this breed, cover has to exist before the first clinical note is written. Three days of delay is enough to permanently exclude the category most likely to be needed.
Generally yes, relative to smaller breeds. Premiums reflect both size, since drug doses, anaesthesia and hospitalisation all scale with a 100 to 150 pound body, and the breed's documented predispositions to orthopaedic, cardiac, urinary and gastric conditions.
It depends entirely on the policy. Some cover hereditary and congenital conditions provided no signs were present before cover started; others exclude them outright. In a breed with documented inherited disease, this clause is the most important one in the document.
Emergency surgery for bloat is the classic example, combining out-of-hours admission, surgery and intensive care in one episode. Total hip replacement is comparable and is planned rather than sudden.
For a breed whose likely problems are chronic and recurring, a policy that renews cover for ongoing conditions year after year usually suits better than one that caps a condition permanently. Compare how each policy handles a problem lasting five years, not one lasting five weeks.
You can usually get cover for other conditions, but expect a cardiac exclusion. It is still worth insuring, since the orthopaedic, gastric and urinary risks in this breed remain entirely uncovered otherwise.
It can be, but the sum has to be honest. Setting aside money each month only works if the fund is genuinely untouched and large enough to absorb an emergency abdominal surgery early in the dog's life, before much has accumulated.
Premiums typically rise with the dog's age regardless, and claims can accelerate that. Check before buying whether the insurer can add new exclusions at renewal after a claim, because that possibility undermines the point of long-term cover.
In the first days of ownership, ideally before any veterinary examination has written anything into the record.
How hereditary and congenital conditions are treated. The breed's documented problems are largely inherited.
Emergency abdominal surgery for bloat, which combines out-of-hours care, surgery and intensive care in one episode.
Because hip and elbow disease often affects both sides, and many policies count both as a single condition against one limit.
Yes. Anaesthesia, medication and hospitalisation all scale with body weight, so identical treatment costs more for a 130 pound dog.
A one-page prep sheet for this condition: the signs, the questions to ask, what to get priced. Unlocks here.
You get: Vet visit prep sheet
No spam. One-click unsubscribe. See our privacy policy.
Preview page 1 before you decide.