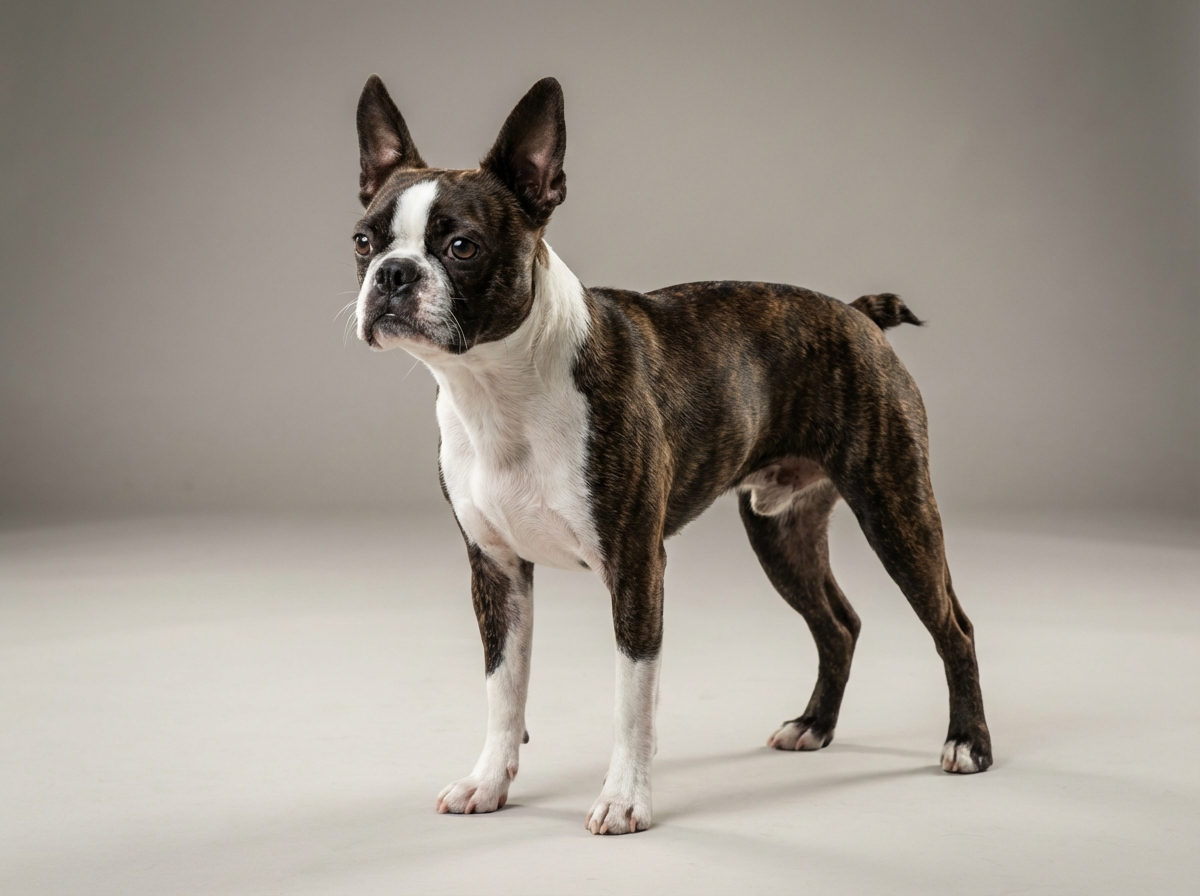
Costs
What do Boston Terrier owners claim for most?
Airway, eye and skin problems dominate, which matches the breed's documented issues of brachycephalic airway syndrome, corneal ulcers, cataracts and allergic skin disease.
Quick answer
What do Boston Terrier owners claim for most?
Airway, eye and skin problems dominate, which matches the breed's documented issues of brachycephalic airway syndrome, corneal ulcers, cataracts and allergic skin disease.
The single most expensive mistake in pet insurance is not choosing the wrong insurer. It is buying the policy the week after a vet wrote something in the file.
New Boston owners comparing policies at eight weeks, and existing owners who have just discovered that the condition their dog needs treated is excluded.
This guide is not medical advice. If your dog shows pain, sudden behavior change, or worsening symptoms, consult a licensed veterinarian.
Some links may be affiliate links. We may earn a commission at no extra cost to you. We only suggest products we believe are helpful for dog owners.
We research and check what we publish, but we do not warrant that any figure, date, price, or statement is accurate, complete, or current, and we accept no liability for any loss, cost, injury, or other harm arising from the use of this site. Use it as one reference among several. You remain responsible for your own decisions and for your dog's care - confirm anything that matters with a licensed veterinarian or another qualified professional before you act on it. Full disclaimer.
Insurance claim patterns are a proxy for the financial reality of owning a particular breed. For Boston Terriers they cluster around the airway, the eyes and the skin, with orthopaedic and heat-related claims behind them. The problem owners run into is not usually finding cover; it is discovering after the fact that the specific thing their dog needed was excluded from day one.
Flat-faced breeds as a group appear disproportionately in respiratory and ophthalmic claim categories relative to their share of insured dogs. Within that group the Boston Terrier is generally less severely affected than the most heavily shortened breeds, but its documented conditions of brachycephalic airway syndrome, cataracts, corneal ulcers, patellar luxation and deafness map directly onto the categories where claims accumulate.
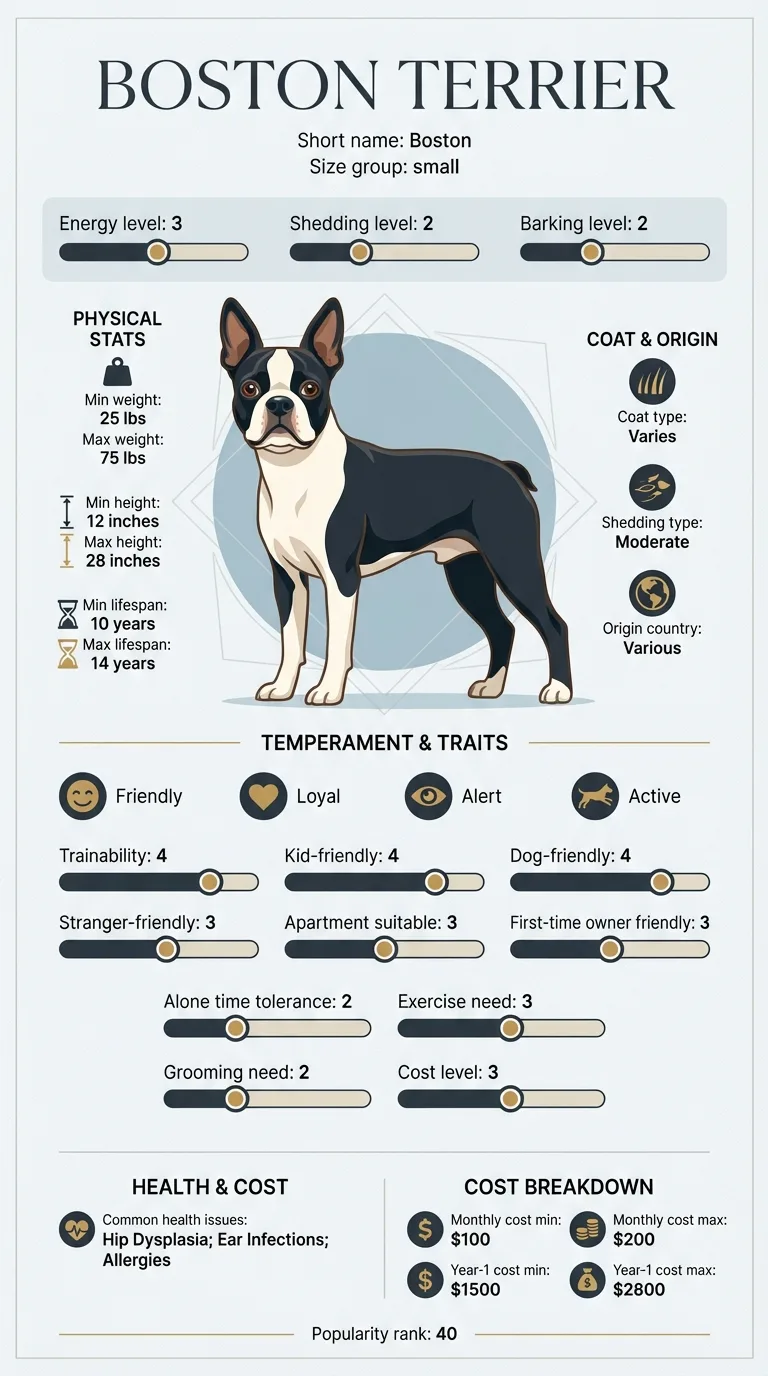
The claim profile is a direct readout of anatomy. A shortened skull produces airway obstruction, and a shallow orbit leaves a prominent eye exposed to injury and drying, which is why corneal ulcers recur. The breed's small 12 to 25 pound frame and lightly built stifle joint underlie patellar problems. Low grooming needs and a short smooth coat mean skin claims come from allergy rather than coat maintenance.
Climate shifts the claim mix. Hot regions generate more heat-related emergency presentations and more airway consultations in summer. Urban dogs living on hard surfaces present differently from rural ones. Owner behaviour matters most of all: households that seek care early generate more small claims and fewer catastrophic ones, which is invisible in aggregate data but decisive for an individual policy.
This is a financial topic, but two clinical points sit inside it. Never delay veterinary care because you are worried about creating a record; an untreated corneal ulcer can cost a Boston its eye within days, and an airway crisis in hot weather is a genuine emergency. Do ask your vet to be precise in notes, distinguishing an observation from a diagnosis, since vague wording is what exclusions are built from. Discuss the likely cost of a recommended procedure before it is scheduled rather than after.
See all Boston Terrier health problems, which breeds are prone to insurance claims, or the full Boston Terrier breed guide for temperament, exercise needs and ownership costs.
Illness waiting periods typically run from two weeks, with orthopaedic conditions often excluded for six months or more from the start date. Premiums usually stay stable for the first few years and rise noticeably from around eight. Claim assessment normally takes days to a few weeks depending on how quickly clinical history is released.
You reach the day your Boston needs airway surgery or cataract assessment and the answer is yes, covered. That outcome is decided almost entirely by choices made in the first fortnight of ownership, not by anything you do at the point of claim.
Claim categories for Boston Terriers track closely to the breed's documented health issues. That correspondence is worth noticing, because it means the health list is not theoretical.
Almost every insurer excludes conditions that existed before the policy started or during an initial waiting period. What surprises owners is how broadly that is applied.
A pre-existing condition is usually defined by what is in the clinical record, not by whether a diagnosis was made. A note reading intermittent snoring, monitor at eight months can be enough to exclude airway surgery two years later. So can a single mention of a skipping hind leg, or one episode of squinting.
Insurers also apply the concept of related conditions. If your Boston was treated for a corneal ulcer in one eye before cover began, an insurer may exclude corneal ulcers in either eye, on the basis that the underlying anatomy is the same. The same logic can link skin infections in different locations to a single underlying allergic tendency.
Waiting periods matter separately. Illness cover typically begins after a couple of weeks, and orthopaedic conditions often carry a much longer waiting period of several months. A puppy insured on the day of collection whose patella problem appears at four months may fall inside that window.
Two practical consequences follow. First, insure before the first veterinary visit if you intend to insure at all. Second, read the definition of pre-existing in the actual policy wording rather than the marketing page, because insurers differ on whether exclusions can be reviewed and lifted after a symptom-free period.

Hattie and Reggie came from the same litter and went to two families in the same town. Both families insured. The difference was three weeks. Hattie's owners bought cover the evening they collected her, before any veterinary visit. Reggie's owners took him for a health check first, where the vet noted mild snoring and slightly narrow nostrils, then insured him a fortnight later. At two and a half, both dogs had airway surgery. Hattie's claim was paid. Reggie's was declined as a pre-existing condition, on the strength of eleven words written when he was nine weeks old. His owners paid the full amount themselves and did not dispute it, because the note was accurate and the policy wording was clear.
Key takeaway: In a breed whose main problems are structural and present from birth, the value of a policy is decided by its start date. Everything else about the comparison is secondary.
Usually somewhat, because insurers price flat-faced breeds higher on the strength of airway and eye claim history. The premium difference is generally modest compared with the cost of a single airway surgery or cataract procedure, which is the trade the pricing reflects.
It depends entirely on timing and wording. Many policies cover it as an illness if no airway sign was recorded before cover began. Some explicitly exclude conditions considered inherent to the breed's conformation. This is the single clause worth reading before buying.
If you plan to insure at all, yes, and ideally before the first veterinary examination. Every visit generates notes, and notes create exclusions. Starting cover on collection day is the cheapest version of this decision you will ever get.
Annual policies reset the condition each year and often stop covering an ongoing problem after twelve months. Lifetime policies keep covering a chronic condition year after year, up to a limit that refreshes annually. For a breed prone to recurring skin and eye problems, the difference is substantial.
Some insurers will review an exclusion after a defined symptom-free period, often two years, with veterinary evidence. Many will not. Ask this question before buying rather than after, because it is not always in the summary document.
It is a good guide to what owners spend on, which is narrower. Conditions that are cheap to manage or that owners treat at home are under-represented, and conditions that lead to euthanasia rather than treatment can look less frequent than they are. Use it alongside the breed's documented health list, not instead of it.
Airway, eye and skin problems dominate, which matches the breed's documented issues of brachycephalic airway syndrome, corneal ulcers, cataracts and allergic skin disease.
It varies widely by region, age, excess and cover level. Expect to pay more than for a similarly sized long-muzzled breed, with premiums rising steeply from about eight years old.
Standard illness and accident policies do not. Vaccination, dental cleaning, spaying and preventive treatment are usually separate wellness add-ons or out of pocket.
You can, but any condition treated under the old policy typically becomes pre-existing under the new one. Switching is easy for a healthy dog and rarely wise once a chronic condition exists.
A one-page prep sheet for this condition: the signs, the questions to ask, what to get priced. Unlocks here.
You get: Vet visit prep sheet
No spam. One-click unsubscribe. See our privacy policy.
Preview page 1 before you decide.