Costs
What's the most common claim type for this breed?
Skin and ear conditions tend to be the most frequently filed, given how often allergies and infections recur over a dog's life.
Quick answer
What's the most common claim type for this breed?
Skin and ear conditions tend to be the most frequently filed, given how often allergies and infections recur over a dog's life.
Before you pick a policy, it's worth knowing which conditions actually generate claims for dogs like yours, rather than reading generic marketing about 'comprehensive coverage.'
This is most useful for prospective owners comparing insurance providers before a diagnosis happens, and current owners trying to understand why certain claims got approved, delayed, or denied under their specific policy's terms.
This guide is not medical advice. If your dog shows pain, sudden behavior change, or worsening symptoms, consult a licensed veterinarian.
Some links may be affiliate links. We may earn a commission at no extra cost to you. We only suggest products we believe are helpful for dog owners.
We research and check what we publish, but we do not warrant that any figure, date, price, or statement is accurate, complete, or current, and we accept no liability for any loss, cost, injury, or other harm arising from the use of this site. Use it as one reference among several. You remain responsible for your own decisions and for your dog's care - confirm anything that matters with a licensed veterinarian or another qualified professional before you act on it. Full disclaimer.
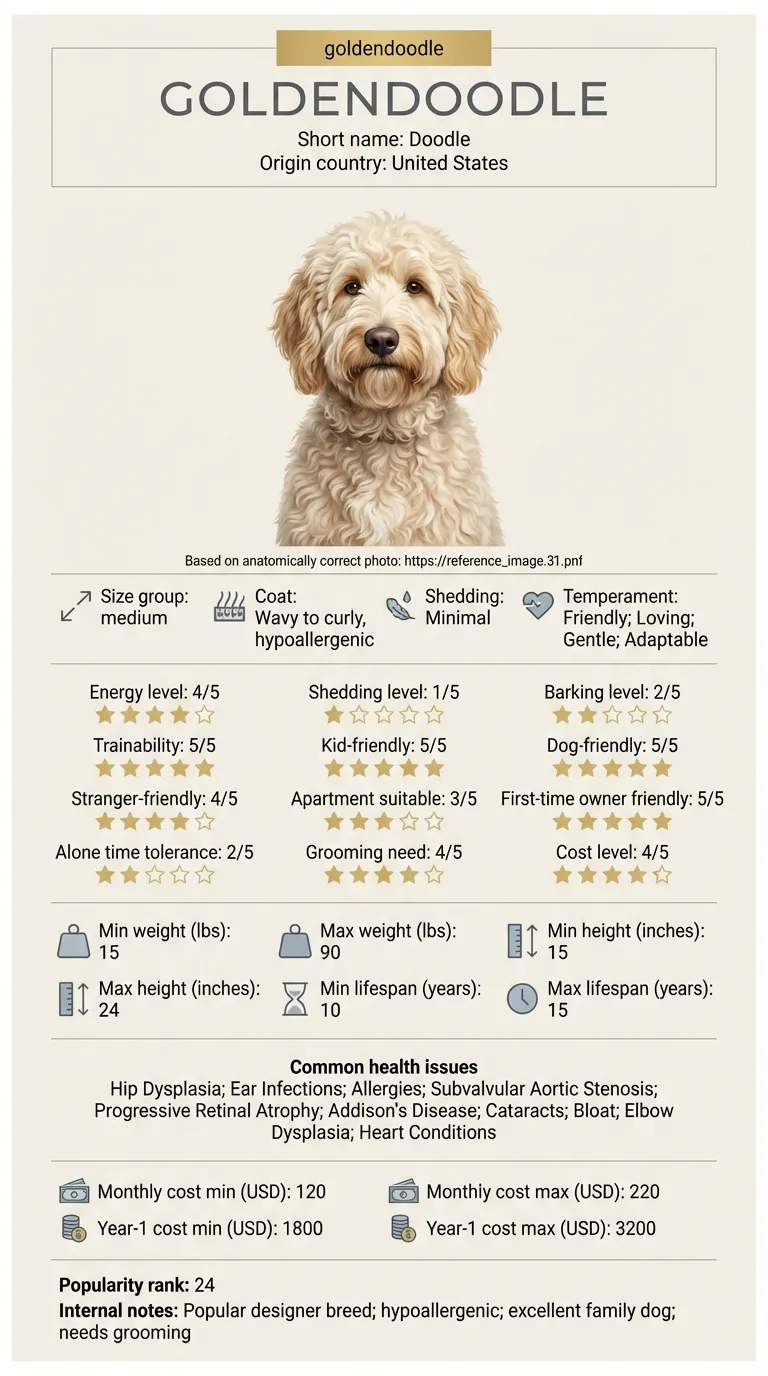
Insurance claim patterns for Goldendoodles reflect a genuine blend of risk from both parent breeds: frequent, lower-cost claims for skin and ear conditions, less frequent but higher-cost claims for orthopedic surgery and cardiac workups, and occasional very expensive claims tied to cancer treatment. Understanding this pattern helps owners choose coverage terms that actually match their dog's realistic risk profile.
Different breeds show varying patterns in insurance claim rates for specific conditions, and Goldendoodles, drawing risk from both Golden Retriever and Poodle lines, show a correspondingly blended claims pattern across orthopedic, cardiac, skin, and cancer categories.
Both parent breeds contribute independently documented risk factors — joint conditions and certain cancers more associated with Golden Retriever lineage, and a mix of skin and other conditions associated with Poodle lineage — which combine in a Goldendoodle's overall claims profile rather than either side canceling the other out.
How and when a dog is enrolled matters enormously here: symptoms documented before enrollment often become excluded pre-existing conditions, and lifestyle factors like consistent weight management or missed screening can shift how much a given condition actually costs to treat and therefore claim over a dog's lifetime.
This is primarily a financial planning topic rather than a medical one, but do ask your vet for an honest read on your specific dog's risk factors at wellness visits, since that context can inform which coverage details matter most for your situation.
See all Goldendoodle health problems, which breeds are prone to insurance claims, or the full Goldendoodle breed guide for temperament, exercise needs and ownership costs.
Comparing providers and enrolling in a policy is typically a same-week decision once you've reviewed a few options. The real payoff of a well-chosen policy often isn't visible for months or years, until a claim actually needs to be filed.
Success looks like a policy whose coverage terms actually match your dog's realistic risk profile, and a claims process that goes smoothly precisely because you understood the fine print before you needed it.
Orthopedic conditions, especially hip and elbow dysplasia, are consistently among the higher-cost, more frequent claim categories for medium-to-large breeds like Goldendoodles, since both parent lines carry documented joint risk and surgical correction for severe cases can run into the thousands. Cardiac conditions, particularly subvalvular aortic stenosis inherited through Golden Retriever lineage, generate fewer claims overall but tend to be higher-cost per claim once cardiology imaging and ongoing monitoring are involved.
Skin and ear conditions are a different pattern entirely: lower cost per individual claim, but far more frequent, since allergies and ear infections tend to recur throughout a dog's life rather than resolve with a single treatment. This pattern of 'frequent but cheap' versus 'rare but expensive' is exactly why the fine print on a policy — annual caps, per-condition caps, and chronic condition handling — matters more than the headline premium.
Cancer claims, while less frequent than joint or skin claims in absolute numbers, tend to be among the most expensive per incident once diagnostics, surgery, and potential chemotherapy are involved, which is part of why some owners specifically compare cancer coverage terms across providers rather than assuming all policies handle it the same way.
Since claim patterns for this breed skew toward chronic, recurring conditions as much as one-time emergencies, the policy details that matter most aren't always the ones insurers advertise loudest.

Sasha insured her Goldendoodle, Finn, as a puppy, choosing the provider with the lowest advertised premium without comparing hereditary condition coverage closely. At eighteen months old, Finn was diagnosed with moderate hip dysplasia. When Sasha filed a claim for the recommended surgery, she discovered her specific policy classified hereditary orthopedic conditions under a separate, lower-cap rider she hadn't purchased. The claim was only partially reimbursed. A friend with a Goldendoodle from the same litter had chosen a slightly more expensive policy from a different provider that covered hereditary conditions under standard terms, and received near-full reimbursement for an almost identical surgery.
Key takeaway: The cheapest premium and the best actual coverage for conditions common in this breed are often two very different policies, and the difference only becomes visible at claim time.
Skin and ear conditions tend to be the most frequently filed claims, given how often allergies and ear infections recur, though orthopedic conditions like hip dysplasia often account for larger individual claim amounts.
It varies significantly by provider and policy. Some explicitly cover congenital and hereditary conditions, while others exclude or limit them, so this is worth confirming in writing before you need to file a claim, not after.
Ideally before — most insurers treat anything noted at a prior vet visit, even a minor comment, as a potential pre-existing condition, which can limit future claims related to it.
Many policies do cover it if it wasn't flagged as pre-existing at enrollment, but surgical procedures like total hip replacement often fall under higher-tier coverage or specific orthopedic riders, so check the exact policy language.
Most comprehensive accident-and-illness policies cover cancer treatment, but annual or per-incident caps can matter enormously here given how expensive chemotherapy and specialist care can get, so check cap amounts specifically.
Premiums vary by age, location, coverage level, and deductible choice, and tend to rise as a dog ages, which is why some owners choose comprehensive coverage while their dog is young and healthier.
Skin and ear conditions tend to be the most frequently filed, given how often allergies and infections recur over a dog's life.
Almost never for the specific condition noted; this is why enrolling before any symptom is documented matters so much.
Only if you add a separate wellness rider; standard accident-and-illness policies typically exclude routine care.
Yes — enrolling before any symptoms are documented avoids most pre-existing condition exclusions down the line.
It depends on your risk tolerance, but a lower deductible generally helps more with the frequent, lower-cost claims common in this breed.
A one-page prep sheet for this condition: the signs, the questions to ask, what to get priced. Unlocks here.
You get: Vet visit prep sheet
No spam. One-click unsubscribe. See our privacy policy.
Preview page 1 before you decide.