Costs
What's the biggest insurance factor for a Brittany owner?
Buying coverage before any documented breed condition, like hip dysplasia or a heart murmur, shows up as a pre-existing condition on the dog's record.
Quick answer
What's the biggest insurance factor for a Brittany owner?
Buying coverage before any documented breed condition, like hip dysplasia or a heart murmur, shows up as a pre-existing condition on the dog's record.
Not all pet insurance policies handle joint conditions, heart disease, or lifelong hormone treatment the same way — and those are exactly the categories most relevant to this breed.
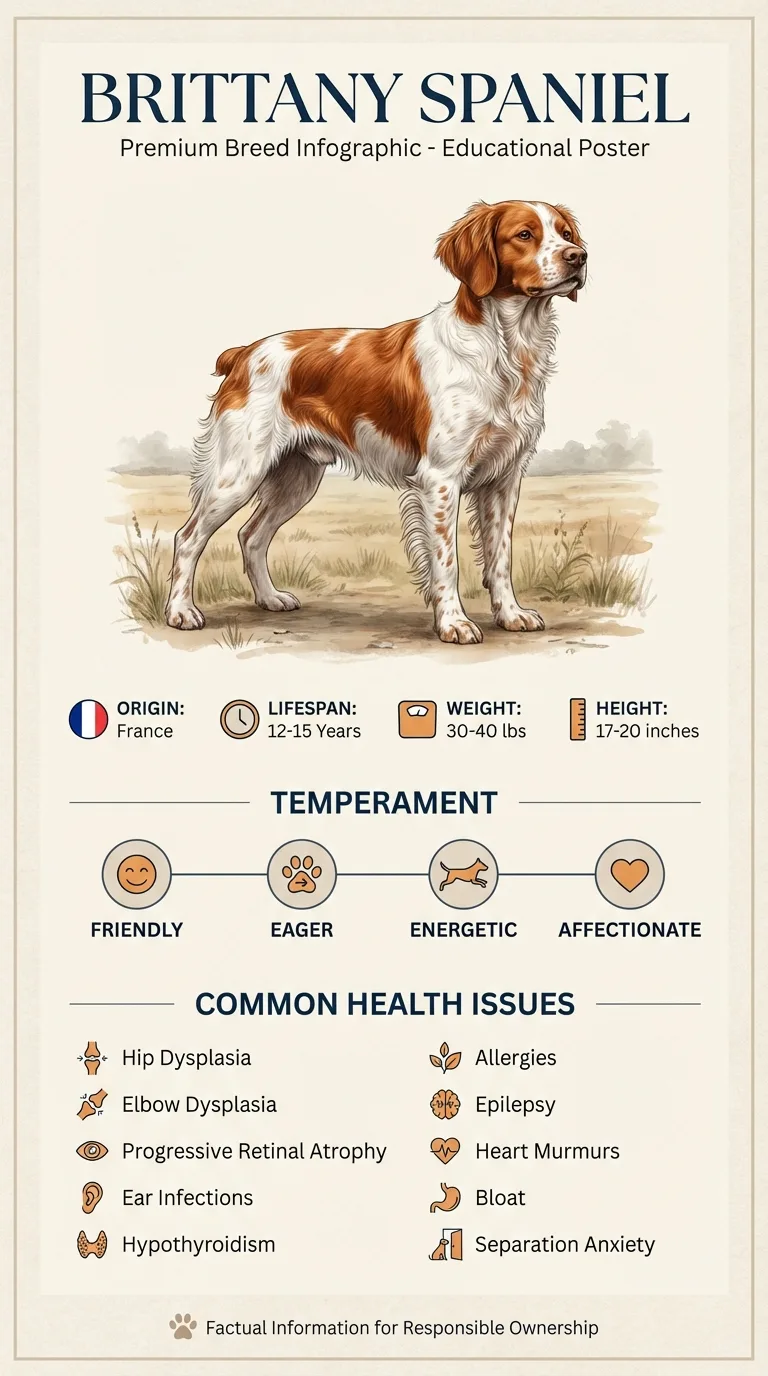
New owners shopping for their first policy often get overwhelmed comparing plans on price alone. Owners of adolescent Brittanys face a different challenge: needing to lock in coverage before a condition like hip dysplasia or a heart murmur becomes a disqualifying pre-existing condition on a new policy.
This guide is not medical advice. If your dog shows pain, sudden behavior change, or worsening symptoms, consult a licensed veterinarian.
Some links may be affiliate links. We may earn a commission at no extra cost to you. We only suggest products we believe are helpful for dog owners.
We research and check what we publish, but we do not warrant that any figure, date, price, or statement is accurate, complete, or current, and we accept no liability for any loss, cost, injury, or other harm arising from the use of this site. Use it as one reference among several. You remain responsible for your own decisions and for your dog's care - confirm anything that matters with a licensed veterinarian or another qualified professional before you act on it. Full disclaimer.
Insurance claim patterns aren't random across breeds — they tend to track a breed's documented health tendencies fairly closely. For Brittanys, a breed with orthopedic issues, heart murmurs, hormone disorders, bloat risk, and separation anxiety all named on its documented health list, that gives a fairly clear roadmap for which categories of coverage actually matter most when comparing policies.
Because these categories are directly tied to conditions already documented as common in this breed, they represent a realistic, above-average likelihood of generating a claim over a Brittany's lifetime compared to a breed without a similar documented health profile.
A breed's documented health issues are, by definition, the conditions that show up often enough in that breed to be worth naming, which makes them a reasonable proxy for what an insurance claim is statistically more likely to involve over a Brittany's lifetime.
How proactively an owner screens for and manages known risks, plus how early insurance is purchased relative to any symptom onset, has a major effect on whether coverage actually pays out when it's needed most.
Ask your vet for documentation of any screening results or wellness findings when applying for or renewing insurance, since accurate records help clarify what is and isn't a pre-existing condition if a claim is ever disputed.
See all Brittany health problems, which breeds are prone to insurance claims, or the full Brittany breed guide for temperament, exercise needs and ownership costs.
Most insurers apply a short initial waiting period, commonly two to four weeks for illness coverage, after a policy starts. Coverage decisions and claim reimbursement timelines vary by provider but are typically processed within a few weeks of submission.
Success looks like a policy purchased early enough to actually cover the conditions this breed is documented to be prone to, rather than discovering a gap in coverage only after a diagnosis has already been made.
None of this guarantees your specific dog will develop any of these conditions, but it's a reasonable checklist for comparing how thoroughly different insurance providers actually cover the categories most relevant to Brittanys specifically.
Pre-existing condition exclusions are the single biggest factor in whether insurance ends up useful for a Brittany. Because conditions like hip dysplasia or a heart murmur can be present without symptoms for a long time, buying a policy while a puppy is young and undiagnosed is what actually secures coverage, rather than waiting until a condition on this breed's known list has already been flagged at a vet visit.
Also worth checking specifically: whether a policy treats bilateral conditions, like hip dysplasia in both hips, as one exclusion or two once one side has been diagnosed, and whether hereditary conditions common in a documented breed list are covered at standard rates or carry a surcharge or waiting period.

When a new owner brought home her eight-week-old Brittany puppy, she enrolled him in an accident-and-illness insurance plan within the first month, well before any vet visit had flagged anything. At eighteen months, a routine exam found a soft heart murmur. Because the policy predated any symptom or diagnosis, the subsequent echocardiogram and ongoing cardiac rechecks were covered as new, non-pre-existing findings. Her policy has since also covered thyroid bloodwork after a hypothyroidism diagnosis at age five, both conditions she specifically knew to watch for from this breed's documented health list.
Key takeaway: Insurance bought before a breed-documented condition ever shows symptoms is what actually determines whether it gets covered later — waiting until a problem appears is usually too late.
Given this breed's documented risk of orthopedic issues, heart conditions, and lifelong hormone treatment, insurance purchased while young and healthy can meaningfully offset costs that would otherwise be significant out-of-pocket expenses.
As early as possible, ideally before any symptoms of a breed-documented condition appear, since pre-existing condition exclusions are based on when a condition is first noted, not when the policy is purchased.
Many accident-and-illness plans do cover hip dysplasia treatment, including surgery, if the condition wasn't diagnosed or symptomatic before the policy started, though some plans price hereditary conditions differently.
Often yes. Some insurers cover documented hereditary conditions like hip dysplasia at standard rates, while others apply waiting periods, sub-limits, or exclusions specifically for conditions known to be common in a given breed.
Coverage varies significantly by provider. Some include behavioral conditions and related medication under illness coverage, while others exclude behavioral treatment entirely, so this is worth confirming directly.
Focus on orthopedic and chronic condition coverage terms, any breed-specific exclusions or waiting periods, and whether ongoing management costs like thyroid medication are covered as illness treatment.
Buying coverage before any documented breed condition, like hip dysplasia or a heart murmur, shows up as a pre-existing condition on the dog's record.
Many illness plans cover ongoing prescription costs for a diagnosed condition like hypothyroidism, though this varies by provider and plan tier.
Yes — bloat is a documented emergency condition in Brittanys with high surgical costs, making emergency GI coverage a meaningful factor when comparing plans.
That's actually the ideal time to buy, since a healthy, undiagnosed dog has no pre-existing conditions yet to be excluded from coverage.
Coverage is inconsistent across providers, so it's worth confirming directly if separation anxiety treatment matters to you for this breed.
A one-page prep sheet for this condition: the signs, the questions to ask, what to get priced. Unlocks here.
You get: Vet visit prep sheet
No spam. One-click unsubscribe. See our privacy policy.
Preview page 1 before you decide.